Story Highlights
- The S&P 500 gained 0.37% while the Nasdaq increased 0.83% on Tuesday as tech stocks recovered from recent losses
- Nvidia surged 2.3% following a four-session decline, with chipmakers Advanced Micro Devices, Broadcom, and Micron Technology also posting gains
- Midterm election results did not significantly impact market performance, though Democratic gains could lead to increased AI regulation
- The recovery concluded a brief selloff that began last week, ending the Nasdaq’s worst monthly performance since March 2025
What Happened
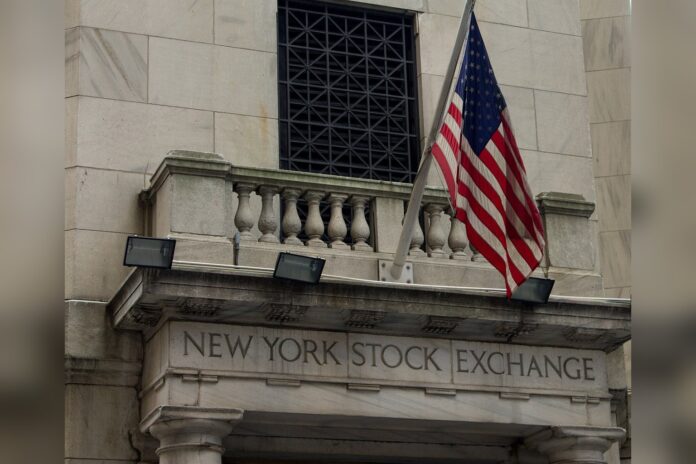
US technology stocks rebounded on Tuesday afternoon, recovering from a recent selloff that had prompted concern among investors regarding artificial intelligence spending levels. The market’s recovery occurred on the day of midterm elections, though election results themselves did not appear to produce substantial market disruption. Broader market indices showed mixed performance, with the S&P 500 closing up 0.37% and the Nasdaq gaining 0.83% for the trading day. The Dow Jones Industrial Average declined 0.38%, partly influenced by a 1.9% drop in Apple’s share price following the company’s release of a lower-than-expected margin forecast attributed to elevated memory chip costs.
Semiconductor stocks led the technology sector’s recovery. Nvidia achieved a 2.3% gain after declining over four consecutive trading sessions. Fellow chipmakers also participated in the upward movement, with Advanced Micro Devices, Broadcom, and Micron Technology all posting gains on Tuesday. The recovery marked the conclusion of a tech sector selloff that had begun the previous week, during which the Nasdaq experienced its largest monthly decline since March 2025. The index had ended the previous trading day in correction territory, having dropped 10% from its October 6 record close.
- S&P 500 up 0.37%, Nasdaq up 0.83%, Dow down 0.38% on Tuesday
- Nvidia gained 2.3% after four-session decline; AMD, Broadcom, and Micron Technology also advanced
- Apple declined 1.9% due to margin forecast concerns related to memory chip costs
- Nasdaq experienced its largest monthly decline since March 2025 during October
Why It Matters
The technology sector’s recovery carries significant implications for broader market sentiment and investor confidence in artificial intelligence as an investment theme. The rebound on election day suggests that market participants maintain confidence in tech valuations despite recent volatility and concerns about AI spending efficiency. The performance of semiconductor stocks is particularly noteworthy given their central role in powering artificial intelligence infrastructure and applications. This recovery indicates that investors may be distinguishing between temporary valuation concerns and longer-term structural growth opportunities in the technology sector.
However, the potential for increased regulatory scrutiny presents a countervailing risk to technology investors. Democratic electoral gains could translate into more aggressive regulatory frameworks for artificial intelligence development and deployment. Such regulation could affect spending patterns and profit margins for technology companies currently benefiting from the AI investment boom. The modest nature of Tuesday’s gains suggests that investor optimism remains tempered by uncertainty regarding both regulatory outcomes and the sustainability of AI spending growth.
- Tech sector recovery demonstrates investor resilience and ongoing confidence in artificial intelligence investment thesis
- Semiconductor stocks’ performance directly reflects demand for AI infrastructure and computing power
- Potential Democratic regulatory initiatives could increase compliance costs and constrain growth for technology companies
- Market volatility indicates ongoing investor caution regarding valuation levels and spending sustainability in AI sector
Political and Public Context
The midterm elections occurred amid broader economic concerns regarding inflation and cost of living pressures affecting American households. Despite these consumer-level economic challenges, Wall Street markets have maintained substantial gains throughout 2025, driven principally by investments in artificial intelligence technologies and related infrastructure. The S&P 500 has gained 10% year-to-date, while the Nasdaq and Dow have advanced 9% and 7% respectively. This divergence between consumer sentiment regarding economic conditions and equity market performance reflects investor optimism regarding technology sector prospects and artificial intelligence’s transformative potential.
Historical analysis of post-election market behavior provides context for Tuesday’s performance. Research examining market performance following midterm elections from 1980 through 2024 indicates that equity markets typically experience gains following election outcomes, after periods of pre-election volatility driven by uncertainty. Wall Street markets often experience heightened volatility prior to elections when outcomes remain unclear, but tend to recover once electoral results are settled and market participants can assess policy direction with greater certainty. The Tuesday market movement aligns with this historical pattern, suggesting that election-related uncertainty may have been a contributing factor to the recent selloff.
- Democratic electoral gains position party to advance artificial intelligence regulation agenda
- Consumer concerns regarding cost of living contrast with robust equity market gains in 2025
- Historical market analysis shows typical post-election recovery following pre-election volatility
- Investor focus on AI infrastructure spending continues despite macroeconomic uncertainty
What Happens Next
Technology sector performance in coming weeks will likely depend on several interconnected factors including regulatory developments, corporate earnings reports, and broader macroeconomic data. The new legislative environment following midterm elections will provide clarity regarding artificial intelligence regulation prospects, which could influence technology stock valuations. Investors will be monitoring Congressional composition and any early legislative initiatives directed toward AI governance. Additionally, corporate earnings reports and forward guidance from major technology companies will offer market participants information regarding AI spending sustainability and profitability implications.
Commodity price movements, particularly in energy markets, will continue influencing broader market sentiment. The decline in crude oil prices to approximately $103 per barrel, down from $117 at October’s conclusion, reflected easing geopolitical tensions and potential negotiations involving Iran and Russia. Continued moderation in energy costs could support consumer purchasing power and corporate profit margins, benefiting equity markets more broadly. Technology sector investors should anticipate potential volatility as markets digest regulatory implications of election outcomes and assess corporate guidance regarding artificial intelligence investments and returns on those investments.
- Regulatory developments regarding artificial intelligence governance will significantly influence technology sector valuations
- Corporate earnings reports and forward guidance will clarify artificial intelligence spending sustainability
- Geopolitical developments affecting energy prices could influence broader market sentiment and consumer confidence
- Technology sector volatility likely to persist as markets assess regulatory environment and corporate profitability implications